Alan Greenspan Quotes
I had made a mistake in presuming that the self interests of the organizations of organizations, specifically banks and others, were such that they were best capable of protecting their own shareholders and their equity in the firms.
Greenspan accepted this as many other economists and financial regulators did. What they did not take into account was the incredible greed of many of the financial executive who were betting with their customers money, If the bet was right they, the shareholders and the customers all made out very well as they were highly leveraged. If the bet was wrong, the shareholders and customers lost a lot, and the financial executives only made their multimillion dollar salaries and bonuses (Many were actually were guaranteed their bonuses even if they put the company into bankruptcy.) Worse, they earned their money when they made their sales or earnings targets, but when the securities they bought went sour, even if the company had no funds left, the. It was “heads we all win and tails only I win.” The vested interests between the financial company executives, the shareholders, and the clients were divergent, and the customer was at the bottom of the money pole.
Alan Greenspan, Chairman, Federal Reserve Board, Congressional Testimony, 2008
Sourced by: Eigen's Political and Historical Quotations

Greenspan was not the amoral fool that this quotation makes him seem. Despite the fact that he was the most important financial officer of the country, he had an ideological faith that a free market was self-corrective in a democracy. The financial industry would police itself he believed. He also trusted the self interest of the financial corporations to restrain them from getting too greedy -- {637989}. He and many others were wrong and most Americans paid the price.
Greenspan and some others assumed that the shareholders and the executives who ran the financial institutions had the same vested interests. But the executives had disconnected themselves from the fate of the shareholders, by having Golden Parachutes to protect the executives even if the business failed and they were fired. And they got their bonuses immediately so by the time the authorities and the shareholders discovered that the profits the bonuses were paid for were illusory, the bonus money was safely stored in a secret offshore bank. But if things went wrong, there was always the play of getting a government bailout which would keep the executives getting their huge bonuses and keep the shareholders from losing their money as the taxpayers covered most of the losses.


The result was regulation of the banks and the creation of the SEC to regulate the stock market, However, over the years, the regulations were not able to keep up with the sophisticated development of new forms of investments and financial instruments and the financial industry were able to speculate with other people’s money in ways that FDR and his reformers never imagined. Finally, even the regulation that did exist was weakened by the policies of the George W. Bush administration and the combination brought about the Great Recession of 2008 where the profits from excess speculation were privatized and the losses, socialized with the taxpayer and the American worker bearing the brunt while most of the speculators were bailed out and made more money than ever. The Obama administration tried to reform the situation, but was unable to put an end to the legal speculation with other people’s money or of having institutions that were “too big to fail.”

At the time, the financial industry spent more money for lobbyists and campaign contributions than any other sector of the economy. The result is that they had extraordinary access to and influence upon members of Congress and their staffs, that more often than not, the actually drafted the language for laws, amendments and regulations and then les the strategy to pass the legislation or finalize the rule. Moreso than any other industry, they wrote their own rules. Even after the Meltdown of 2008 and the Great Recession where there was a public outcry for reform, the Dodd Frank legislation was influenced by the industry and after passage most of the rules and interpretations were written by the industry or greatly influenced by them.
This quotation is particularly interesting in it shows how far partisanship and ideology can go into deluding political perception. Wallinson is a man of integrity who we must assumed believed what he said. Yet in the 30 years he referred to, most had Republican Presidents and there were a number of Republican controlled Congresses. During all that time the Republican Party platform called for continuous deregulation. Every Republican President and even Democrat William Clinton has bragged about their success at deregulating the business and financial environment in America. During that period, left wingers paraded to testify to Congress that the deregulation policies and practices was in their view injuring the country, While there was great debate over the desirability of deregulation, virtually no elected politician of the left or right denied that deregulation was happening. The Chamber of Commerce during that time always complained that the deregulation was not occurring fast enough and consumer groups claimed the rate was too fast. Yet Wallinson instead of taking the position of most conservatives that the deregulation had little or nothing to do with the Financial Crisis of 2008, actually convinced himself that there had been no deregulation. Human perception of political reality can be easily altered by ideology. Similar delusions have also occurred for left wingers. It is the ideology who is vulnerable regardless of what the ideology is.

This extreme view of regulation is one of the many views that caused the Nevada voters to reject her.

This warning was a decade before the Meltdown of 2008, but was not heeded by any of the politicians. As a result a number of the companies that made all those risky decisions assumed that if something went terribly wrong the government would not let them fail. Unfortunately, they were right and the taxpayers spent billions to prevent companies from failing. After the meltdown all the politicians vowed to end the too big to fail concept, but while some improvements were made, the Congress could not come to agreement, and the markets and a number of companies think that they are still too big to fail. This is particularly true for Defense Contractors where the government has and probably will in the future, protect irresponsible companies from failure if they are the only company that makes needed weapons and other equipment.


He was referring to Fannie Mae, the government-created. private mortage guarantee company. It was heavily regulated, and in general it met the regulatory requirements. However, the requirements were insufficient, and in the 2008 Meltdown and the Great Recession that followed, Fannie Mae itself was in such bad financial condition, that the Federal Government had bail them out or have the entire home mortgage industry fall apart.


Modern finance is so complex and convoluted, that any laws or regulations that government makes are quickly evaded by even more complex and convoluted schemes which the legislators and regulators have to try and control. By the time they learn and understand and finally develop measures to regulate those, the cycle starts again. Hence the “fool’s errand”

4 years after the Great Recession where major banks of America needed government bailouts to prevent failure the Administration and Federal Reserve board wanted to increase the capital requirements to increase the safety of the Banks. Essentially the banks would speculate and gamble with depositors’ money. If their investment paid off, there were large profits and bonuses for the executives. If it did not, they ran out of capital as they had very little of their own at risk. The government bailed them out and the executives got their bonuses anyway. The efforts to make the banks speculate with more of their own money were strongly opposed by the banks and bank executives.


For many general government regulations—labor, environment, non discrimination—the small business has a proportionately heavier burden of compliance. So large businesses have always been able to count on small business to lobby against regulation and for deregulation. However, when it comes to financial regulation such as the Dodd-Frank regulations essentially apply to large businesses. As a matter of fact, small businesses were on many ways the most frequent victims of the large banks and investment bank excesses in the Meltdown of 2008. Before most of the regulations could even take effect, the financial industry was already trying to get small business to lobby to roll back the protective regulations preventing future meltdowns and bank failure resulting from loose regulation and greedy irresponsible financial industry behavior. The President campaigned to convince the small business not to support the finance industry over their usual “knee jerk” reaction to any regulation.


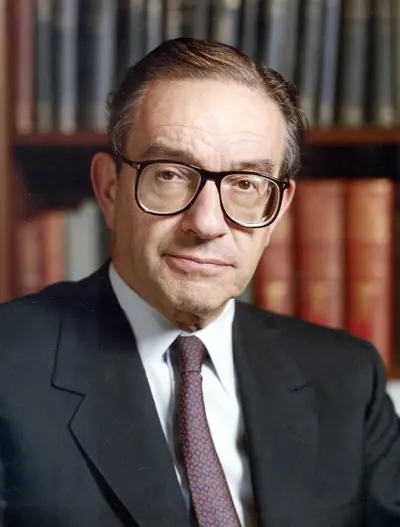
- Born: March 6, 1926
- Nationality: American
- Profession: Economist
Alan Greenspan is an American economist who served five terms as the 13th Chair of the Federal Reserve of the United States from 1987 to 2006. He works as a private adviser and provides consulting for firms through his company, Greenspan Associates LLC. First appointed Federal Reserve chairman by President Ronald Reagan in August 1987, he was reappointed at successive four-year intervals until retiring on January 31, 2006, after the second-longest tenure in the position (behind William McChesney Martin).
