Martin Wolf Quotes
No industry should have the capacity to inflict economic costs that may even surpass those of a world war.
Martin Wolf, British Financial Writer, Editor & Commentator, Chief Economics Commentator, The Financial Times, Referring to the Worldwide Financial & Banking Industry, The Shifts and the Shocks: What We’ve Learned—And What We Still Have To Learn—From The Financial Crisis, 2014
Sourced by: Eigen's Political and Historical Quotations


The election of Franklin Delano Roosevelt for a third term


Born thought that her agency was responsible for regulating the new esoteric financial products—derivatives including credit default swaps—for otherwise there would be no regulation at all of financial products that could dwarf the stock and bond market. Summers persuaded her to back off. When the Meltdown of 2008 hit, the huge derivative exposure of the large banks and some insurance companies was so great that it was one of the major causes for the meltdown of the entire banking system. Summers, normally a great economist not only called this one wrong, but later, along with most other government and private economists ignored a very explicit warning—See {637168}, {637986}, and {620038}.

Many companies appear to be doing much better than they really are. Often they employ PR professionals to create that impression. Some companies are not even solvent, but the only way we can all tell is to have a recession generally or in that particular sector—the equivalent of the tide going out.

Geithner, the Treasury Secretary immediately after the Meltdown of 2008, facing complete collapse of our financial system, among other ameliorations, advocated and implemented many subsidies to bail out the banks most of whom had been greedy, foolish and often dishonest. He even allowed banks to use taxpayer money to pay bonuses to Bank executives who had brought the bank to ruin being a cause of the crisis. However, the banks not only survived but recovered and made huge profits while many of the taxpayers whose funds were used to help the banks were still struggling to make ends meet and it was they who received little, if any, government assistant.


1st Viscount Grey of Fallodon


The Federal Trade Commission is


Conservatives are surprised to learn that their great economic nemesis was one of the early economists who saw the danger of paper money and government control over the minting of money which is one of their core concerns.
Honore Gabriel Victor Requiti. France was in desperate financial condition and the "radical" notion of an income tax was proposed and debated but the rich nobles violently objected. The tax was not enacted. The French Revolution followed. The nobles lost more than part of their income.


by stopping all interest payments on Federal Debts. because Jefferson would dismantle the Navy. Hamilton, a Federalist was supporting John Adams for a second term, and created lies that made the 2012 Republican prevarications against Barack Obama seem like innocent fibs. These 3 lies covered the areas which candidates ever since have gotten mileage out of attacking the opposition. 1) He is fiscally irresponsible and would ruin the economy. 2) He does not support the Constitution. 3) He is unpatriotic and would weaken the military. These have been the 3 favorite areas for lying about an opponent ever since. As in {629237} each of the lies has a grain of truth in it to make it more believable. Jefferson had been an opponent of the Federal Government assuming the States’ Revolutionary War debts, but he never favored defaulting on the interest after the debt was assumed and when elected always paid the interest. Jefferson was representing the United States in France when the Constitutional Convention was held and was not a part of its creation. He was critical of parts of the Constitution and was one of the many who demanded that a Bill of Rights be added. Therefore Hamilton claimed he was against the Constitution. Jefferson was opposed to a standing professional army. It turned out that when he was President. he not only built up the Navy but used it to attack the Barbary States who were assaulting our ships. These were just the biggest lies; the Federalists had many more, and Hamilton enumerated several in this article.
Keynes thought that within 100 years, governments could control economies so that recessions and depressions would not tale place and a sufficient standard of living could be maintained so that poverty would be eliminated. By the end of the 20th century, no nation had accomplished this and few tried. By the 21st century, globalization made it impossible for a single nation or even a small group of nations to control a nation’s economy.
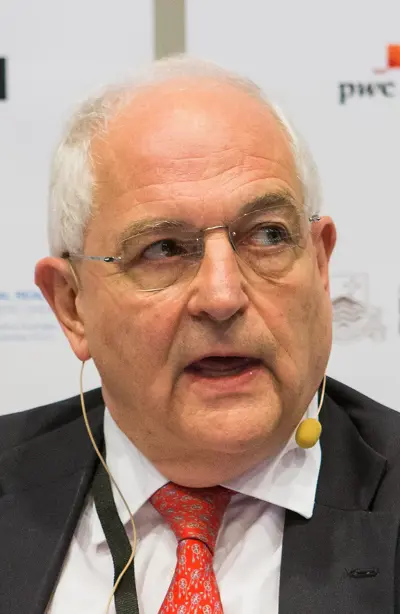
Martin Harry Wolf CBE is a British journalist who focuses on economics. He is the associate editor and chief economics commentator at the Financial Times.
